Ads
US stocks post worst session since 2025 on Nov 6 2026
khoảng 3 giờ trước
001. WALL STREET SELLS OFF AFTER MIDTERM ELECTIONS
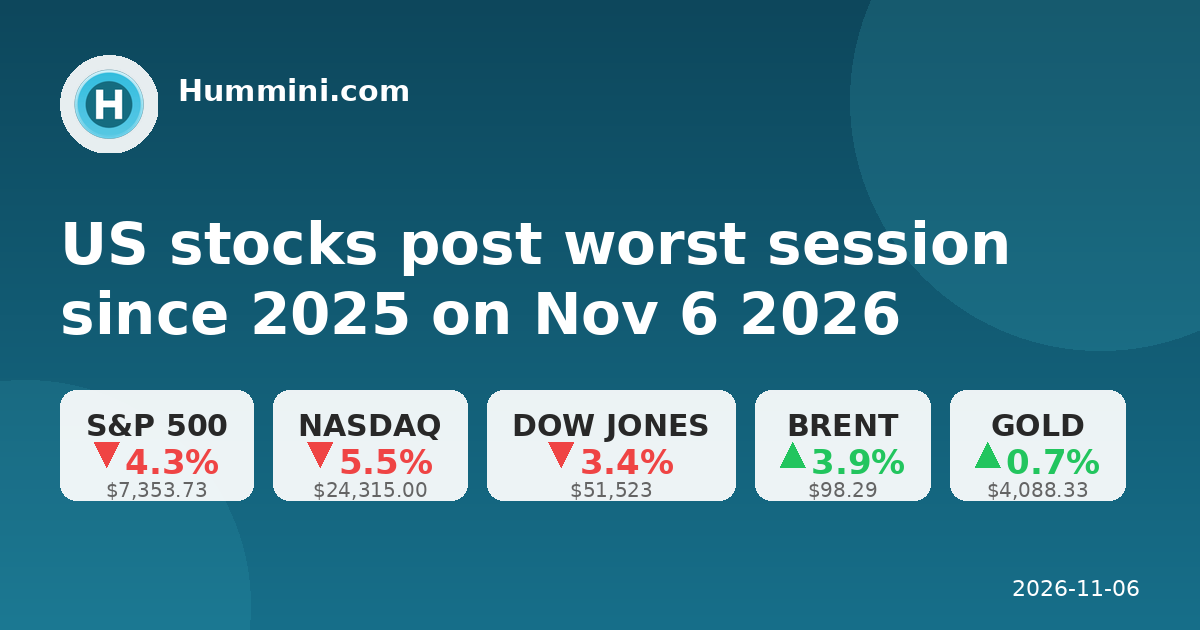
On Nov 5, the Dow fell 1,834 points (-3.44%) to around 51,523; the S&P 500 dropped 334.8 points (-4.35%) to 7,353.73; the Nasdaq Composite tumbled 1,421 points (-5.52%) to 24,315, entering correction territory after falling roughly 12% from its October high. The VIX jumped 61.9% to 26.89. All 11 S&P 500 sectors closed lower; the Nasdaq 100 lost about $1.9 trillion in market value and the S&P 500 lost about $3 trillion. Investors linked the slide to Democratic midterm gains in both chambers, stoking concern over tighter AI/data-centre regulation, scepticism about AI capital spending and elevated Treasury yields. Nvidia fell about 9%, Broadcom about 9.4%, AMD about 15-17%, Micron about 15%, and the Philadelphia Semiconductor Index slid about 10-12%.
2. GLOBAL MARKETS SPLIT AFTER US TECH ROUT
Canada's S&P/TSX Composite dropped 736.13 points (-2.03%) to 35,605.27, its steepest one-day fall since June 5; technology shares slid 3.8%, with Celestica down 12.7%. In Europe, the Stoxx Europe 600 fell 0.38% to 654.87; the FTSE 100 fell 0.43%; the DAX 40 fell 0.43%; France's CAC 40 rose 0.34%; Italy's FTSE MIB lost 1.03%; Spain's IBEX 35 gained 0.59%. Asian trading on Nov 6 was mixed: the Hang Seng rose 3.67% to 24,797, India's Nifty 50 rose 2.60% to 79,310, the Shanghai Composite edged up 0.10%, while the Nikkei 225 fell 1.79%. The divergence suggests regional investors are weighing the US tech shock against local factors.
3. BOE RAISES BANK RATE FOR FIRST TIME SINCE 2023
The Bank of England raised Bank Rate by 25bps to 4.00%, its first increase since August 2023, by an 8-1 vote; Catherine Mann voted for a 50bp move. The BoE forecast UK inflation near 5% by mid-2027 and warned that further hikes may be needed if the US-Iran conflict keeps energy prices elevated. The decision marks a renewed tightening stance in the UK, with implications for borrowing costs and global rate expectations.
4. FED DECEMBER HIKE EXPECTATIONS COOL
The Federal Reserve held rates at 3.75%-4.00% last week, but Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented in favour of a hike. Hammack said rates need to reach restrictive territory to bring inflation back to 2% in a timely manner, favouring more frequent, smaller adjustments; Richmond Fed President Tom Barkin said more hikes are coming at a gradual pace. Rate-futures pricing for a December increase fell to about 66-69% from about 83% as the equity selloff pushed Treasury yields lower.
5. OIL REBOUNDS ON HORMUZ TANKER ATTACKS
WTI for December settled up 2.72% at $90.52 a barrel; Brent for January settled up 3.88% at $98.29 a barrel. Oil was still down about 11% this week after Wednesday's 8-9% plunge on expectations of a Middle East peace deal following the US midterms. Iran reported three more tankers damaged in the Strait of Hormuz; Reuters cited sources saying President Trump could order a resumption of hostilities after the midterms, but this remains unconfirmed. Qatar continued mediation between Washington and Tehran, with no binding agreement reached. Eurasia Group said renewed escalation would likely push Brent into a $110-$125/barrel range.
6. GOLD RISES AS TREASURY YIELDS FALL
Spot gold settled around $4,088.33/oz, up 0.69%, after touching $4,147.00/oz, its highest since Oct 20; Anadolu Agency reported gold up 0.6% to about $4,080/oz. Spot silver fell 0.79% to $51.793/oz on industrial-demand concerns. The US 10-year Treasury yield fell to about 4.82%, the lowest since early September, while the 2-year yield was near 4.48%, as investors sought havens.
7. US LABOUR DATA REMAIN TIGHT
Initial jobless claims for the week ending Oct 31 fell by 6,000 to a seasonally adjusted 189,000, below expectations of 196,000 and the fewest since mid-July; continuing claims rose. Third-quarter nonfarm business productivity rose at a 3.6% annualised rate, above expectations of about 2.7-2.8%, while unit labour costs fell 0.7% versus expectations of an increase. The data eased some wage-inflation concerns, though the October jobs report was not confirmed at the time of compilation.
What to watch today: The US October jobs report is due at 13:30 GMT on Nov 6; consensus expectations are for nonfarm payrolls of about +65,000, unemployment steady at 4.2%, and average hourly earnings up 0.3% month-over-month.
*Summary information for reference only, reflecting various sources at the time of posting.*
0 comments
Ads
Related Posts
Ads