Ads
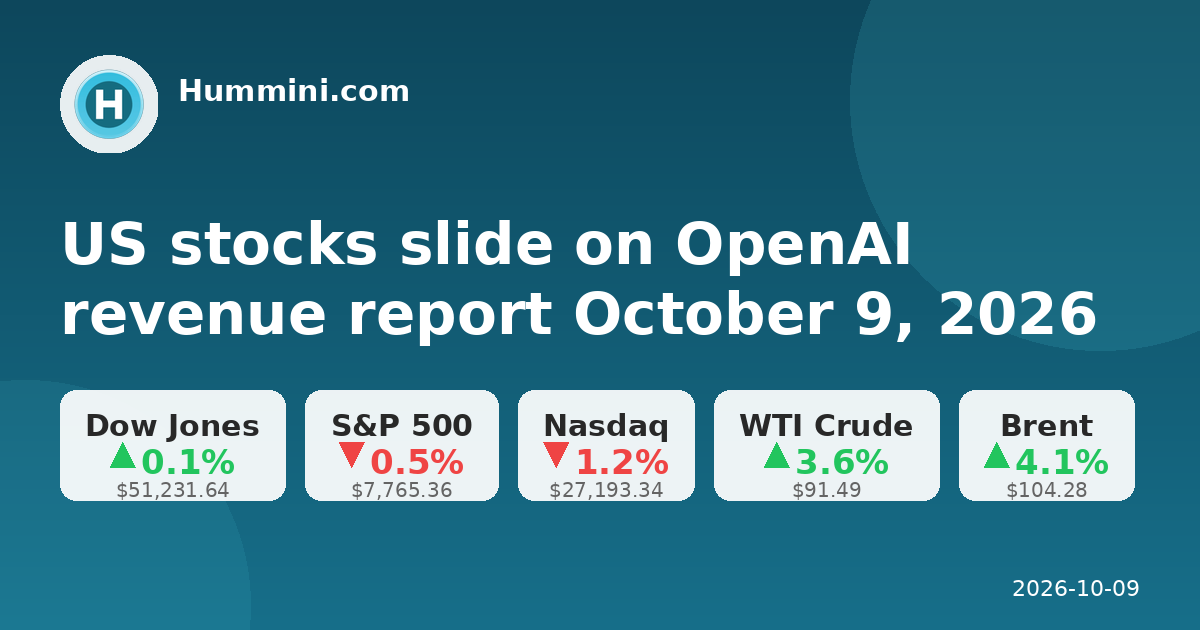
US stocks slide on OpenAI revenue report October 9, 2026
khoảng 1 giờ trước
001. US EQUITIES FALL - Nasdaq drops 1.25%.
US equities saw heavy selling in tech on Oct 8 after the Financial Times reported that OpenAI had told investors annualized revenue was near $50bn at end-September, roughly $18–20bn below the $68–70bn cited previously. This has not been officially confirmed by OpenAI. The Dow added 0.10% to 51,231.64, but the S&P 500 fell 0.47% to 7,765.36 and the Nasdaq Composite lost 1.25% to 27,193.34. The Philadelphia Semiconductor Index dropped 3.4%, with Nvidia -2.9%, Micron -4.8%, Broadcom -4.3%, Oracle -5.8% and TSMC -3.0%.
2. OIL PRICES JUMP - Brent tops $104 a barrel.
WTI crude for November rose 3.6% to $91.49/bbl, the biggest one-day gain in a month; December Brent rose 4.1% to $104.28/bbl, the highest since late September. Drivers included Iran stepping up attacks on tankers in and around the Strait of Hormuz, Hurricane Isaias shutting in about 1.3 million barrels per day or 62.9% of US Gulf of Mexico oil output, and surging freight costs. Donald Trump said the US would not strike Iran before the November 3 midterms, trimming intraday highs.
3. HORMUZ STRAIT TENSIONS - Tanker hit north of Qatar.
The UK Maritime Trade Operations (UKMTO) said a tanker was struck by multiple projectiles north of Qatar with casualties; this information has not been independently confirmed. Weekly attacks on Hormuz shipping reached their highest level since the US-Iran conflict began. The US Treasury imposed new sanctions on 17 vessels and networks transporting Iranian crude, petroleum and petrochemical products, adding to global supply and shipping-cost risks.
4. ASIAN EQUITIES FALL - China returns from holidays.
Shanghai Composite fell 0.79% to 3,811.90, Shenzhen Component lost 2.07% to 12,620.89 and ChiNext dropped 3.15% to 3,036.66 in the first session after China's National Day holiday; funds rotated from tech into defensive and resource sectors. Hang Seng fell 1.43% to 23,785.79 and Hang Seng Tech lost 2.89% to 4,073.38. Nikkei 225 fell 1.42% to 69,042.11, while KOSPI declined 1.98% to 6,803.90.
5. MACRO DATA MIXED - US jobs, German exports diverge.
US initial jobless claims fell 2,000 to 197,000 in the week ended October 3; continuing claims rose 17,000 to 1.716 million. Germany's August exports fell 0.8% month-on-month to EUR 137.6bn, missing the expected 0.6% increase and marking a second straight monthly decline. China's foreign exchange reserves at end-September reached $3.4003 trillion, down $38.1bn or 1.11% month-on-month.
6. CENTRAL BANK SIGNALS - Fed and ECB stay cautious.
ECB September meeting accounts showed all policymakers saw inflation risks as skewed to the upside, with no pre-commitment on the future rate path; the 2.50% deposit rate was seen within the neutral range. In the US, St. Louis Fed President Musalem said more policy firming is needed to return inflation to 2% in a timely manner, while Governor Waller said further rate hikes are likely. CME FedWatch put the probability of an October Fed rate hike at roughly 17% and December at 81%.
7. CORPORATE NEWS - Starbucks eyes Chipotle; PepsiCo mixed.
The Financial Times reported that Starbucks worked with advisers on a takeover proposal for Chipotle; Chipotle jumped 6%, while Starbucks fell as much as 6.7% intraday, its biggest drop in over a year. PepsiCo posted Q3 revenue up 5.6% to $25.27bn, beating estimates, but cut FY26 core EPS growth guidance to 2.5–3%. Amazon cut nearly 1,000 jobs in its stores business.
What to watch today: Official response from OpenAI to the Financial Times revenue figure and the US equity session on October 9 after the tech sell-off.
*Information is compiled for reference and reflects multiple sources at the time of publication.*
0 comments
Ads
Related Posts
Ads