Ads
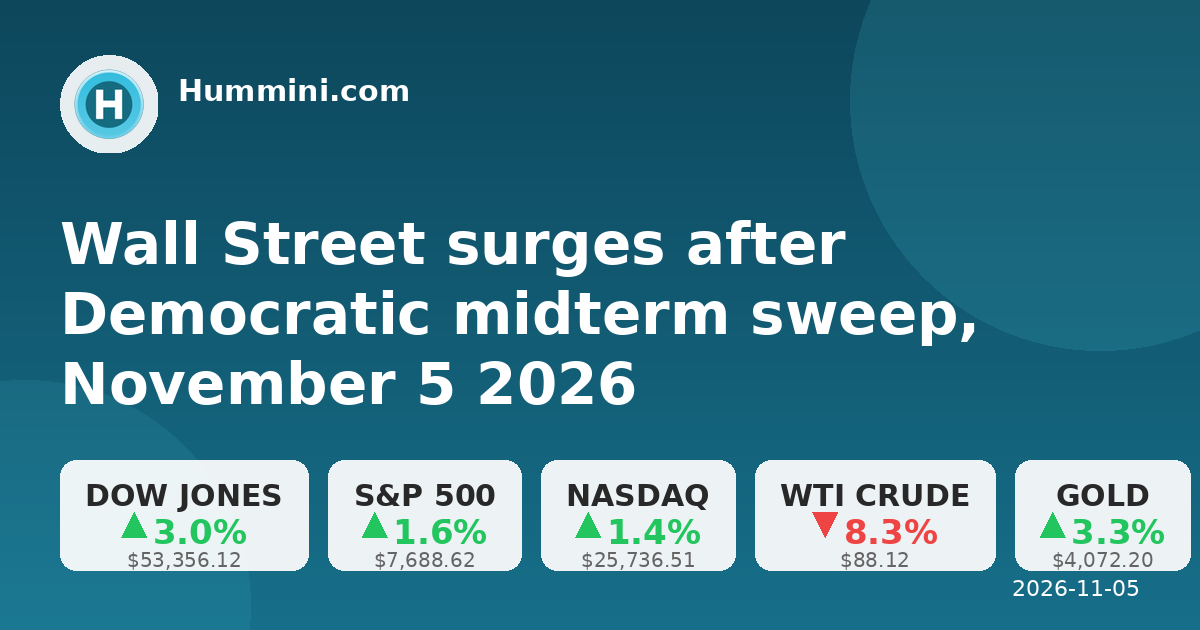
Wall Street surges after Democratic midterm sweep, November 5 2026
khoảng 1 giờ trước
001. US MIDTERM SWEEP REMOVES POLITICAL OVERHANG
Event: Democrats won control of both the Senate and House on November 3, and President Trump accepted the outcome. Context/impact: Wall Street rallied on November 4; the Dow rose 1,569.40 points, or 3.03 percent, to 53,356.12, its best day since April 9, 2025 and first close above 53,000 since September 8. S&P 500 gained 1.58 percent to 7,688.62 and Nasdaq added 1.44 percent to 25,736.51. Consumer discretionary rose 4.27 percent, financials rose 3.46 percent, while energy dropped 4.77 percent. Microsoft, Amazon and Apple rose more than 5 percent; Nvidia and data-center names fell on AI regulation concerns; Trump Media & Technology Group fell about 24 percent and Tesla fell about 3.9 percent.
2. CRUDE OIL PLUNGES ON IRAN DE-ESCALATION BETS
Event: WTI December delivery fell 7.97 dollars, or 8.29 percent, to settle at 88.12 dollars a barrel; Brent dropped 8.67 percent to 94.62 dollars, the lowest settlements since August 31. Context/impact: OPEC reported 2026 crude shipping and insurance costs have soared; on the Middle East-to-East Asia VLCC route, freight per barrel rose from 3.18 dollars in late January to 37.13 dollars at end-October, and insurance from 0.06 to 12.29 dollars, lifting shipping and insurance to about 30 percent of total crude cost versus roughly 3 percent normally.
3. PRECIOUS METALS RALLY AS DOLLAR AND YIELDS FALL
Event: COMEX December gold rose 3.34 percent to 4,072.20 dollars an ounce, silver rose 5.17 percent to 52.33 dollars; the US dollar index fell 0.30 percent to 101.57. Context/impact: The 10-year Treasury yield fell 6.8 basis points to 4.892 percent; EUR/USD rose 0.30 percent to 1.1223, GBP/USD 0.39 percent to 1.3468, and USD/JPY slipped 0.15 percent to 158.49. Bitcoin climbed above 80,000 dollars, according to The Edge Malaysia.
4. US AND EUROZONE DATA PAINT MIXED PICTURE
Event: The US goods and services trade deficit was 105.0 billion dollars in September; imports rose 1.2 percent to a record 426.6 billion and exports rose 1.9 percent to 321.5 billion. ADP private payrolls rose 86,000 in October, above the 65,000 consensus; ISM services PMI fell to 54.5 from 54.9, a three-month low. Context/impact: Eurozone annual HICP inflation rose to 4.0 percent in October, the highest since September 2023 and double the ECB target; the composite PMI was revised down to 51.7, a four-month low.
5. CENTRAL BANKS: BRAZIL HOLDS, BOE IN FOCUS
Event: Brazil's central bank kept the Selic rate unchanged at 13.75 percent on November 4, pausing its easing cycle on asymmetric inflation risks and fiscal uncertainty; the People's Bank of China conducted 300 billion yuan of outright reverse repos on November 5. Context/impact: The Bank of England is due to issue its rate decision on November 5; economists expect a 25-basis-point hike to 4.00 percent, the first increase since August 2023. ECB's Knot and SNB's Schlegel flagged sticky inflation pressures.
6. GLOBAL EQUITIES FOLLOW WALL STREET HIGHER
Event: Germany's DAX advanced 2.22 percent, the UK FTSE 100 rose 1.79 percent, and the Euro Stoxx 50 gained 1.97 percent; Hong Kong's Hang Seng rose 1.67 percent to 23,919.50; Shanghai Composite rose 2.16 percent, Shenzhen Component 4.22 percent, ChiNext 6.40 percent and STAR50 9.92 percent, with turnover above 2 trillion yuan. Context/impact: Reduced US political uncertainty and a weaker dollar supported risk appetite, while the Hang Seng Tech Index added 1.77 percent.
7. KEY EVENTS ON NOVEMBER 5
Event: The US releases initial jobless claims for the week ending October 31, with consensus around 196,000 versus 194,000 prior; eurozone PPI for September is expected at 2.5 percent month-on-month versus 1.9 percent prior. Context/impact: The Bank of England rate decision and Governor Bailey's press conference will be the main policy focus, with potential implications for sterling and global yields.
What to watch today: Bank of England rate decision and Governor Bailey press conference, alongside US initial jobless claims.
*Information compiled from multiple sources for reference at time of publication.*
0 comments
Ads
Related Posts
Ads