Ads
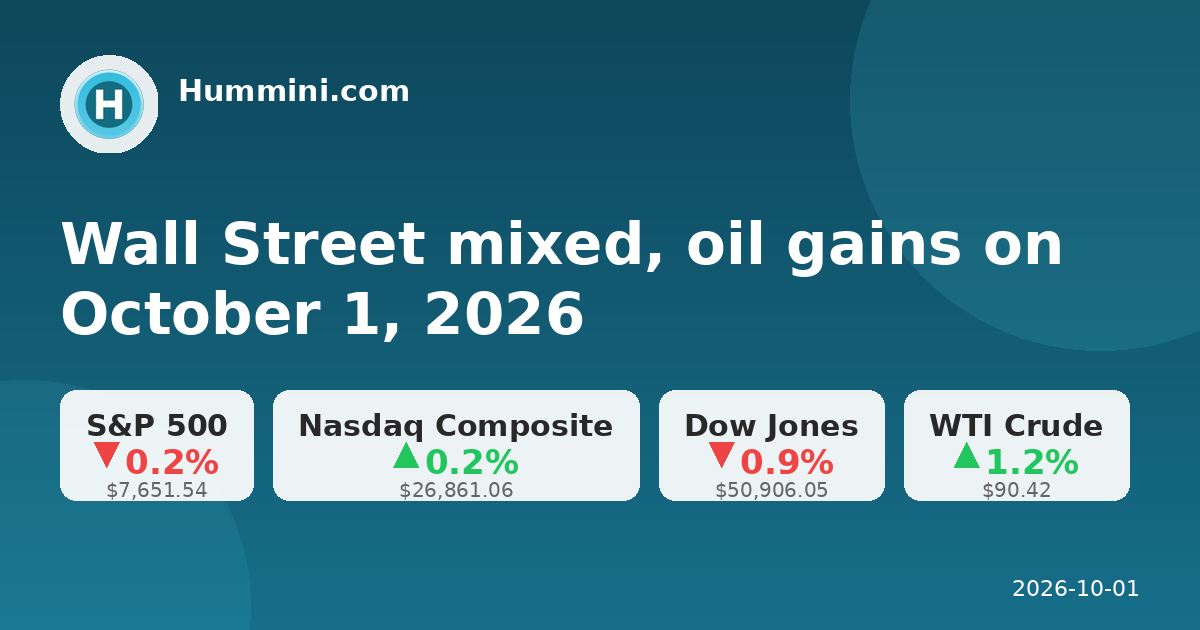
Wall Street mixed, oil gains on October 1, 2026
khoảng 1 giờ trước
001. WALL STREET REVERSED LATE IN THE SESSION.
The S&P 500 fell 0.25% to 7,651.54, the Dow Jones lost 0.86% to 50,906.05, and the Nasdaq Composite added 0.24% to 26,861.06. An early rally after softer US inflation data faded into the close; the S&P 500 posted its worst month since June with a September decline of 0.45%.
2. CORE PCE CAME IN BELOW EXPECTATIONS.
The US core PCE price index rose 3.0% year-over-year in August, below the 3.3% consensus; headline PCE rose 3.4%, also below the 3.7% forecast. Money markets cut the odds of an October Fed hike to about 39% from around 45%, while December hike odds stayed near 90%.
3. FED PASSED STRESS-TEST CHANGES WITH DISSENT.
The Federal Reserve approved stress-test reforms by a 6-1 vote, cutting capital-requirement volatility by about half and introducing two-year averaging from 2028. Governor Michael Barr dissented, warning the changes weaken bank resilience; President Trump disputed a separate inspector general report on the Fed's $2.4bn headquarters renovation and threatened a lawsuit to remove former Fed Chair Jerome Powell from the board.
4. LONG-DATED YIELDS AND THE DOLLAR ROSE.
The 30-year Treasury yield rose for a seventh session to about 5.63%, the highest since 2002; the 10-year sat near 5.28-5.29%. Global government bonds were on course for their worst quarter since 2024, while the dollar index rose to 101.489 and recorded its best month since March.
5. OIL GAINED AMID US-IRAN STALEMATE.
WTI November settled up 1.16% at $90.42 a barrel and Brent rose 0.92% to $103.53. US-Iran talks remained stalled, EIA data showed gasoline and distillate inventories fell by 1.7 million and 2.3 million barrels respectively, and OPEC+ was expected to keep November output targets unchanged at its Sunday meeting.
6. IRAN SAID IT RECEIVED A US RESPONSE.
Iran said it received an official US reply to its proposal to reopen the Strait of Hormuz and end the seven-month conflict. According to reports not independently confirmed, the 'seven-day plan' content was not disputed and differences narrowed to implementation sequencing; the US had not released an official account.
7. RUSSIA EXTENDED DIESEL EXPORT BAN.
Russia extended its diesel export ban until the end of October, while US diesel prices were near $6.53 per gallon, up more than 70% since the Iran-related conflict began. The White House urged the EU to release emergency diesel stocks and President Trump was reportedly weighing a US diesel export ban.
8. MICRON POSTED RECORD REVENUE BUT SHARES SLIPPED.
Micron reported fiscal Q4 revenue up 379% year-over-year to $54.23bn, beating the $51.07bn consensus; adjusted EPS was $33.42 versus $31.61 estimated. Its Q1 FY2027 revenue guidance also exceeded estimates, but the adjusted gross margin forecast of 86.3% missed the 86.7% consensus on higher bonus costs, sending shares down about 0.5% after hours.
9. BOEING WON A MORE THAN $20BN NAVY FIGHTER CONTRACT.
The Pentagon selected Boeing to develop the sixth-generation F/A-XX carrier fighter, beating Northrop Grumman. The award strengthens Boeing's naval fighter position and could reshape US defense competition.
10. FOREIGN INVESTORS SOLD KOREAN CHIP STOCKS.
Foreign investors net sold about 16.45 trillion won of Samsung Electronics and SK hynix shares in September. South Korea's KOSPI fell around 18.8% in Q3, the worst major market globally, though it remained up about 60% year-to-date.
11. CHINA'S OFFICIAL PMI RETURNED TO EXPANSION.
China's manufacturing PMI rose to 50.1 in September from 49.8, and the non-manufacturing PMI climbed to 50.2 from 49.0. Mainland and Hong Kong markets were closed on October 1 for National Day, delaying an immediate market reaction.
What to watch today: Asian futures are set for a volatile start after Micron's results, ahead of Friday's US nonfarm payrolls.
*Information is aggregated for reference and reflects multiple sources at the time of publication.*
0 comments
Ads
Related Posts
Ads